
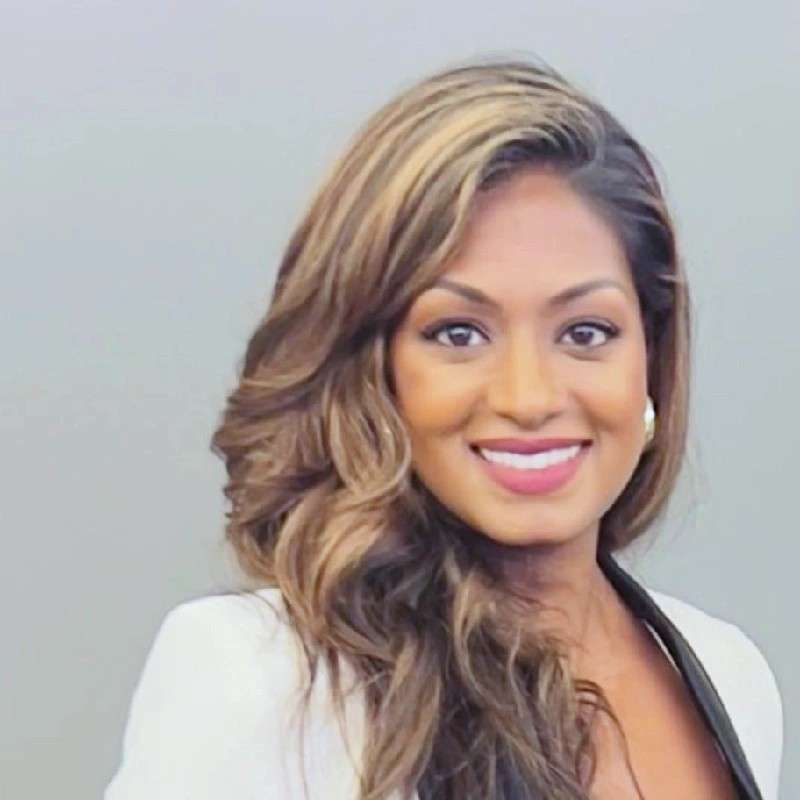
In this episode of Get Hired Up, Maureen Farmer speaks with exit advisor Sankeetha Selvarajah about the complexities of selling a business. They explore the importance of proactive exit and succession planning, the role of advisory boards, family dynamics, and the emotional challenges of transitioning away from a company that has become part of an owner’s identity. The conversation also highlights how a successful exit can create opportunities for personal reinvention and a fulfilling next chapter.
Transcript
Maddie: Welcome to the Get Hired Up podcast. I’m Maddie Shears, producer of the podcast, and I’m here with Maureen Farmer, founder and CEO of Westgate. Maureen, today’s conversation is about business exits, but having listened to it, I’m not sure this is really an episode about selling a company.
Maureen: I don’t think it is either, Maddie. So, a business exit may be a transaction, but for the person who built or led the business, it can also be a profound leadership and life transition. And our guest today is Sankeetha Savaraja, an attorney, business strategist, and executive advisor who works with founders, owners, sellers, and buyers navigating these complex business transitions. And of course, says We know, this is St. Keith’s second visit to get hired up, and our conversation went into some fascinating directions. We talked about why business owners sometimes sell reactively, the role of advisory boards, succession and family dynamics, and why an owner’s identity can become so intertwined with the company that the financial transaction may actually be the easier part of leaving the business behind.
Maddie: Yes, it’s truly a compelling conversation. There’s also a fascinating question running through the conversation. What happens when someone has spent Years preparing the business for an exit, but hasn’t prepared themselves or their family for what comes next?
Maureen: Exactly. And we have a really interesting example in the podcast of that very thing. And that’s particularly relevant to the work we’re doing here at Westgate. So we advise senior leaders navigating these consequential career and leadership transitions. And an ownership transition can be one of the most consequential of all. And of course, the decision isn’t simply when should I sell or what’s the business worth? It can become who am I without this company? What do I want my next chapter to look like? And what decisions should I be making now to preserve my options later? Agency, we call it here. Sankeetha has a wonderful perspective on all of this, including her observation that after an exit, people sometimes give themselves permission to explore parts of themselves they’ve been quietly nurturing for years. I absolutely love that. Here’s my conversation with Sankeetha Salvarajah.
As a six times nationally awarded startup attorney, Sankeetha Salvarajah does more than create profitable exits for her clients. With almost 15 years of legal and business consulting experience, she’s passionate about creating better businesses by making law accessible to business owners. No matter which role she’s playing, her goal is very simple to educate founders and business owners to enable themselves to drive measurable results. Sankitha, welcome back to the Get Hired Up podcast.
Sankeetha: Thanks for having me. Appreciate it, Maureen.
Maureen: Oh, it’s my absolute pleasure. I’m very curious about your journey from MA lawyer to business strategist to all of these things that you’re doing. Could you just give us a little bit of a sense of your most recent journey?
Sankeetha: So, recently, I really switched over to exit advisory, which has been a lot more fulfilling for me because I get to remain at that 30000 foot area while I’m helping founders and owners and exiters, as well as buyers on their exit journey. So, it allows me to See future trends as well as assist in the present moment as well. And I don’t want to say it’s curiously fulfilling because I had glimpses of this before, but now that I’ve stepped into it more, it has been one of the most fulfilling parts of my career journey, so to speak. And I don’t even feel like it’s a career. It’s just a great way to spend a day, actually. So you know what they say, if you really like what you do, it’s not really work.
Maureen: Absolutely. And I’ve heard that before. I experience that myself in the work that I’m doing as well. The podcast is a passion project. I love sharing people’s expertise with listeners. And you know, when you and I spoke last time on the podcast, the very last point that you made, this was episode 76 for the listener in case you want to go back and listen to this conversation. You said the very last thing you said is that people make business decisions based off of emotions. I’d like to start by sharing a couple of statistics that are very recent, and the exit planning council I believe is the name of it organization. 51% of privately held US businesses are owned by baby boomers approaching transition and only 20% to 30% of businesses brought to market actually sell. The third one is 85% of owners hope to create a lasting legacy for their family yet only 54% have a formal succession plan. A successful exit rather requires more than a buyer, it requires preparing the business, the owner, the family. And the next chapter. So with that start I would love to ask you what’s the biggest difference between when we spoke two years ago and today? And then, if you could address some of these statistics and if they align with your experience.
Sankeetha: o, because we’re in the silver transfer, the silver resignation is really what that is, is as you noted, we’re set to transfer about 5 trillion in the next five to 10 years based off of these baby boomers that are transitioning out. And what is interesting is that. The fact that most of these are baby boomers have no succession plan. Okay, so either they have children or subordinates or junior partners that just aren’t interested in running the company in the sense of owning the company. And so a lot of that money is going to be made by buyers that are getting these companies at fire sales. So the biggest advice that I can give for any baby boomer is to plan an exit you will get more on your ROI if you actually plan it rather than Not planning it, because at that point you will then allow a buyer to name your price and you’ll take it at that point. So that’s what I meant by most business owners, and at this point I’m talking about exiters, are people that definitely just want to sell their company but have not put any thought into it. They just want to get rid of it. Now that’s a very distinct position rather than strategically planning for it and making a decision from an alpha position rather than a beta position at that point.
Maureen: For sure. Can you explain the difference between alpha and beta? So beta is market value and alpha is a premium return on investment. Would that be the difference?
Sankeetha: There’s also an Intangible side of it is where an alpha is where you are alpha in the negotiation, okay? In the sense that you get to call the shots because you know what your bottom line is and where your best case offer and where your worst case offer would be, okay? So you decide, you decide going into that negotiation so you know when you’ll walk away. Anybody that’s planned an exit will enter into a negotiation in the alpha role because you’re not just taking the first offer, okay? Whereas if you do not plan an exit or you come in just seeing what will come of it Course, take any call, any offer, and consider it, but don’t consider it blindly. And you don’t have to, like marriage, you don’t have to marry the first person that flirts with you. So you do want to be strategic, and don’t take any offer without consulting your advisors along that path.
Maureen: So this is a question I have. You mentioned a fire sale, just want to get rid of it, it sounds to me as though that’s a very reactive position. So I’m guessing there’s some type Of a trigger event that is precipitating that.
Sankeetha: So a fire sale generally happens when a seller wants to get rid of a company for a number amount of reasons. So they are approaching bankruptcy, they want to get some money for it, they want to dissolve the company because they’re burnt out, there’s no successor, and it’s quickly losing money. Okay, so they want to get the most value out of it while it actually has some asset value. Okay, so all of these things are situational reasons for deciding upon a fire sale, it’s because of a trigger within the company, or it’s an internal trigger within the owner, that’s causing the fire sale.
Maureen: What about the family? What about the owner’s family?
Sankeetha: So that depends if the owner’s family Is kept abreast of what’s happening with the company, number one. Okay. Sometimes owners usually keep their family out of it unless the family is already part of the business. Now, if the owner’s family is already part of the business, it is a family business. And so clear communication needs to happen as to who is going to be taking over the company and if they’re going to be okay with any outside buyer coming in and buying it. Now, if the owner has not kept their family abreast of the situation, then harder questions come into play. As to what happens when that source of income is gone, or what happens if the family is dependent on that income or that status of owning a company, et cetera, et cetera, the trappings of success that were associated with the owner’s company.
So there’s layers to this. And obviously, we also recommend every time you’re planning for a sale, most people think you just need a CFO, an attorney, a wealth management professional, but I would highly, highly recommend a money therapist. Or even just a therapist to talk about this big transition, life transition that’s about to happen, especially if you plan an exit. Now, if you don’t plan an exit, all of those individuals and service providers will still be in the mix, but now you’re getting them after the point rather than before the point, which is when would really solidify your position as an alpha going into a negotiation.
Maureen: So we talked about, you know, the emotional side of this exit. I’d like to talk about the difference between. A reactive sale or a fire sale, if you will, or that type of an exit versus one that’s well planned. Can you kind of compare and contrast?
Sankeetha: So, reactive sale is generally happens when a buyer makes an offer to a seller and the seller buys reaction, immediate reaction as a quick solution to their temporary problems, which they don’t know is temporary, but feels.
Maureen: Let’s stop there for just a second. Can you explain that a little bit further?
Sankeetha: Yeah. So, and it’s tough because Hindsight is always 20 20, but it’s also maintaining your equanimity throughout the storm. Okay. So, if you are losing money or you’re having a bad year, the revenue’s down, you lost key clients, and you think, and a buyer comes out of nowhere and says, Hey, we’ll give you an offer at this point. Now, that is the buyer’s best dream, right? They want to get you at a low point. Okay. You want to buy low, sell high, right? That applies to all forms of business. And you decide to sell because you think that you won’t replenish your client contracts and the revenues won’t increase. And so you think this is the best I can do. Why don’t I just sell the company right now? That is a purely reactive decision.
Maureen: How often do you see that, Sankeitha? A lot or?
Sankeetha: It happens more often than not. I’ll say that in the sense that in many ways, you don’t know what’s going to happen unless they sell the company. And then afterwards, you see that their industry takes off, right? Their industry as a whole takes off. And you’re just like, well, I should have kept it for a while. It’s like selling a house, and then that whole area just takes off, becomes more attractive, right? So you’re like, oh, I could have held on to it, increased my property value, and sold it later. The same thing applies to a company as well. But I will say this the company’s leadership also determines the company’s revenue, right? It seems kind of redundant to say that. But there is a moment of self awareness that has to happen where instead of selling the company perhaps you may just want to transfer the reins of the company to somebody else in the interim before you sell the company. So you’re being reactive, but not in the sense of giving up the whole company, but just giving up leadership or management for about a year or two to a new CEO or maybe your VP at that time. Okay. So that’s another option rather than selling it. Okay. So there are many different ways to pursue sales, but reactive is probably not one that we recommend.
Maureen: Of course. And so when founders are, I’ll give you an example. I met a business owner from the UK when I was in New York last year. And we met at an event, really, really interesting story, Sankitha. I won’t go into details to protect his confidentiality, but he has a unique construction business in the UK. So this construction business is a family business and, you know, been in the marketplace for a very, very long time, inherited it from his dad. But I feel as though he was in a really good place, Sankitha, because he was, he said, you know, I things are going really well and now I think it’s time for me for a business transition. Because his experience was similar to what you just mentioned, which was the burnout. And he said, it’s a great business, but there is a lot of complexity. And due to the regulatory side of this construction business, it’s very highly regulated in the UK. And he said, I just can’t deal with that anymore. I’m tired. I’m young enough to still have another career and enjoy things, but I don’t want to be like my dad because his dad retired out of the business when he was not well. So I feel like this is a really good case study for us to kind of noodle around because of the his he would be the proactive on the proactive side.
Sankeetha: Oh, and he’s already alpha because he’s learning from other people’s mistakes and also understanding how he can remain detached from the company in order to see his value and what that looks like in this year and the year after, right? And I think sometimes founders sabotage their own growth and exit when they ignore that internal voice as well as advice from external parties. Now, of course, you are the final captain of your ship and you are the one that makes the final decisions, but sometimes when founders have been, and I hate to say founders, at that point, they are owners, full out owners of the company. After owners, there’s a tinge of arrogance that comes with having that longevity as being an owner and that hard experience that sometimes dilutes the actual facts that are there. So you start to look at things differently or think that it’s going to go some way based off the last few years of your leadership. When sometimes having that external, you know, even an advisory board coming in and saying, Hey, I think it’s time we sell, because then it’s forcing you to remove yourself emotionally and remain detached and look at this company as exactly what that is. It’s a company, it’s not an extension of your identity, it’s not an extension of who you are. It’s in a company and making the hard decisions at that point, which means even walking away right when it’s going well, right? So that you want to sell high. So that might be, that’s a strategic move. And he’s also done something that maybe he’s thought of his life after this company.
Maureen: Right. I think he’s probably looked at his dad. And thought to himself, you know, great company has given his family a wonderful quality of life. And, but he wants to spend more time with his children before they graduate from high school because once they’re, you know, how it goes. And, you know, so he’s very, I think what I’m hearing you say, and I think what we’re agreeing on is that there’s a degree of self awareness going on here
Sankeetha: Yes. And that degree of self awareness is augmented by having an external advisor board come in and have a conversation with you every quarter. So, one, you don’t feel alone in your journey. Number two, and this is just before exit, this is the entire lifeline of your company. You should have some form of informal or formal advisory board that sits on this 30000 feet area and basically advises you on where that is.
And they’re also united in your exit plan at the same time. So, every decision, act, partnership, client that you take on should go towards your exit plan. So, it forces everyone to think to the future rather than maintain or stay in the present.
Maureen: When you think of, I know for my business, I’ve had an advisory board for several years now. We’re pretty boutique, so not a big, big business, but I’m curious your thoughts on when an advisory board should be formed and who should be on that board.
Sankeetha: So, generally, you can have, you should have up to three. You can start with one. But move up to three or five. You want an odd number in case you have to take a vote so there’s no deadlocks. Okay. And you want complementary skill sets. So, finance, for sure, always have a numbers person on there. Okay. So, CFO or some sort of accountant that can think in the current taxable year and the future taxable year as well. And so that can marry the numbers with the story of your company. It seems like a tall order, but you’ll find them as you go along in your journey. And then I would be remiss to say the fact that I’m a lawyer for sure that I would recommend that you have someone with legal oversight as well on there. And then finally, if you have a threeperson team, you want someone that has already exited or has succeeded in your industry to sit on your board. That’s a big one. Yeah, you don’t really want someone that’s complimentary. You want someone that’s already succeeded because then they can advise you on their experience as well. And so they can also talk to you about the industry So they’re industry specific, okay, whereas the other two are skill Specific as well.
Now you can round that out, that’s your immediate three, you can round that out with two others that are situation specific. Say you’re going to launch a product, you can bring an advisor on for the three to six months that you’re about to launch a product, okay, so you can bring those in as like ad hoc adjunct advisors as needed. Now all of these, you should introduce them all together and tell them your plans for the year. Say, this is our revenue goal. This is our market goal. This is what we’re trying to launch. This is what we want to accomplish. So, everybody is brought up to speed on what you would like to do and also unite them on your potential exit plan. I would like to sell my company for 5 million in five years. Sorry for the small numbers, but just as illustration, just to talk through what that looks like. So, all of them are also united and can also advise you on that and say, hey, if we do something. Now, understand in four years you’re going to have an issue because in this industry at this time. So obviously, the legal will advise you on something like, hey, if you want to exit within the next two to three years, we should make sure all your contracts reflect buyer friendly clauses.
So then it becomes purely strategic. Buyer friendly clauses. Okay. Do you see? And then the CFO gets going on how to now build the story around the numbers of your company in order that we can make the sale of your company attractive to a potential buyer. So tell me, what is a buyer friendly clause? What does that mean, Sankitha? So generally, we want to look for clients. We love, buyers love recurring contracts. Okay. Contracts that go beyond the current year. So multi year contracts, if you can have them, or SAS. This is why SAS models are great, okay? Because it’s a subscription model, which continually goes on and on and on monthly until you remember to cancel it or you just continuously just renew it, right? Also, government contracts, if the assignment and the transition of them is allowed, that’s the sticky part. But basically, you’re looking for clauses that don’t prevent the buyer from stepping into your shoes on the date of closing. So it has to be fully assignable and there should be no friction in the transition in that. Okay, so with that also to massage that most owners, especially if you have a family run business or an owner that has a personal touch with the clients, most buyers will ask owners to stay on or to consult for three to six months after the closing so that they can do an introduction between current clients, you know. Where the owner can make a friend Introduction to the new buyer and say, Hey, this is Ted. He’s taking over our company. I know you and client X will get along great. I’d leave it to you guys to continue and start that relationship. ” So it’s a warm introduction so that the client doesn’t feel like there’s new management and doesn’t lose that personal touch. Now I say this because we going back to our first point about how most of these family businesses are going through that great transition in the next five years, right? So all of these are built. Usually built off of personal relationships.
Maureen: According to a recent US bank survey 85 of business owners say they started their business to create something they could pass on and 84 hope to create generational wealth for their family Yet only 54 have a formal succession plan.
Sankeetha: That sounds very true.
Maureen: Has that changed at all over the years Sankeetha?
Sankeetha: When was that study done?
Maureen: Just recent very recent.
Sankeetha: Then I would say that nothing’s changed from that. I would say that’s very, very true for a current point. I think more awareness of the situation is coming up. A lot more people have wealth management that’s also looking at their finances. So they obviously talk about succession for their families and they talk about how do we pass along this wealth. And wealth has so many connotations. Right? So, I personally talk about the wealth quotient value, the WQV, which is wealth isn’t even about money, it’s about how healthy you are, right? So, how much sleep you’ve got, okay? You know, how much community you have, you know? So, um, how much time? I think time is more expensive than money. And so, with that gentleman that you were talking about. He wanted to use his most finite resource, time, to spend it with his kids, yeah. And so, that’s the kind of wealth. That owners really need to spend time on is how do you define wealth? And then how would you now utilize your company to get the most out of your definition of wealth? Yeah. And that’s a tough, like. That’s not a easy one hour exercise. That’s a few long walks with a lot of different trusted advisors, your wealth person, talking to your kids about this, talking to your friends about this, talking to your spouse about this as well. Too. What do they envision their life with you after you’re not in the office 12 to 14 hours a day. You know?
Maureen: I heard a story a few years ago. It was an example, it was a real life example of a business owner who sold his company and did very. Very well and bought a boat. And his vision was to sail around the world with his wife. And she had absolutely no idea about this plan and said absolutely she would not be sailing around the world because she wanted to be with her grandchildren. And so clearly they had not had that conversation.
Sankeetha: They had not. And I hope you got a good resale value on that. Because that is a depreciating asset.
Maureen: Yes. I don’t know what the outcome was, but I thought, wow, you know, how common is that? I’m sure it’s probably pretty common because, you know, sometimes we have our own vision of what the future looks like and, you know, we become attached to it.
Sankeetha: I think that is absolutely true. So understanding family dynamics. What I was discussing before is important because sometimes we find that business owners use the company to escape their family life. And so when you sell the company, you are now faced with what you have been escaping all this time.
Maureen: Yes, you’re forced to face reality. And I think that when I look here and I forget the statistic. I think it’s like 70% of first time transactions don’t conclude something like that for founders, founder owned businesses. It’s a high statistic anyway. I wonder, you know, a lot of business owners will say, well, they didn’t get the financial valuation that they had been hoping for. So they decided not to go through with the transaction, where in fact, the real reason. And this is what the research says, is that there is a lack of emotional fortitude as it relates to that transition. You know, what am I going to do? And then, as you know, we all know, I’ve heard this many times. You know, I retired from my business or I sold my business, and, you know. 12 months on the golf course in Arizona just wasn’t doing it for me.
Sankeetha: Nobody talks about the intellectual boredom that happens after you sell a company. I’ve had it. I’m a 2X exeter myself. After the two, three months of, you know, feeling like I have all this time to spend with my friends, my family, you know, my partner. It was great. But after a while what now? My daily tasks were done at 12 pm what now? But then, you know, inevitably some other business idea happens and so forth. And, you know, life naturally happens. But an interesting little vignette I wanted to share was. That after every seller sells. I usually check in six months after. It’s in my calendar. I put in a note just to check in. 11 times out of 10, they don’t regret selling the company. That’s not the feeling that happens. It’s the feeling that they should have asked for more. Interesting. Yeah. And any regret that they did have was monetary. And then again, this is anecdotal. But the company owners that I’ve worked with were like I think that when they were because they’ve all planned an exit so they knew what they were doing whereas I wonder if I caught Someone that did a reactive sale, if they would feel otherwise. They would be like, maybe I shouldn’t have sold,” and whatnot. And what we had discussed earlier is that maybe when that situation passed, they wouldn’t have sold the company.
Maureen: Yeah. I interviewed a gentleman by the name of Donald Zilka back in January. He’s in New York and he’s an investor. And it was actually at Hinton’s Tech Week conference last year. And you were there. I don’t know if you remember seeing him, but he and another gentleman opened the conference. And at the end of their half hour presentation, I asked Donald this question I said, You know, what has surprised you most in your career so far? And he said that people give up too soon. And then I thought, Well, I have to have him on the podcast. And his point was that there are business cycles that has never changed business cycles, economic cycles. You know, corrections do correct themselves. I knew this intuitively, I’ve held long positions myself in keeping patient and keeping perspective. But that was his point is that people sell too soon, or they sell in a panic, or they give up too soon. And that has that’s really, really resonated with me, because he’s done, he’s worked with organizations, and he holds long, so he’s had conversations companies, you know, in his portfolio for more than 20 years. So I don’t know how you get that perspective. I think it’s maybe learning and listening and getting As you rightly pointed out, having an advisory board that can help you weather those storms.
Sankeetha: I think what also helps is also, and this is the granular here, is knowing the value of all of your assets in your company. So at some point where you may be thinking of selling the whole company, a PSA, purchase and sale agreement, you could think about selling out portions or assets of your company. And that requires you to know the value of each asset and also to think strategically and continuously pull yourself out of being on the ground. And so you have to meet your advisory board at that 30000 feet. It’s working on your business as well as working in your business, isn’t it really? And there you should make time for working on your business because it gives you that perspective of looking at it and also checking in at each meeting. And this is the very, there’s a moment of hubris here where you say, am I still the leader of the CEO that is going to take my company to exit?
Maureen: Right. We’re coming close to that end of our conversation, Sankitha. And I do have a couple of other questions. When it comes to succession and exit planning, when is a good time to start planning? I’m sure it’s as soon as possible. But what are your thoughts on that?
Sankeetha: I mean, there’s this quote that says the best Time to plant a tree is 20 years ago. The next best time is today or tomorrow, right? So, you know, as soon as you have awareness, you should. The minute you start planning an exit, you switch from being a scaler to a sailor or an exit. Yeah. Because then it aligns your North Star at that point, right? So instead of thinking about this fiscal year and the next fiscal year, you’re thinking about the end point. And then everything works backwards from that point. So even if you don’t have One right now, it’s okay. Even having a cheap and nasty one right now just to flirt with for the weekend, you can say, what if I sold my company for 10 million?” Well, you have to make your company book valued for 10 million at least to get some value out of it. And then understanding the value of each of your assets. So understanding how much your IP is worth. How much your client contracts are worth, how much your systems are worth, and then just really working through that with your CFO, and then thinking about potential buyers that would buy each part. The second part of planning an exit is also thinking like a potential buyer and saying, what kind of buyer would buy my company?
This goes hand in hand with looking at your company and the leadership. Are you still the same person to run this company? Is this company still saleable to a potential buyer? So once you start thinking like a buyer and understanding your exit plan, it slowly fills in place. Okay. And as time goes on, you also start thinking strategically. So once you’ve figured out your exit plan, I would like to sell the company for X amount at this time. So five years and for five million. Then going through your Assets, understanding your bottom line, because at that point, you would have to make some hard decisions. You have to kill some darlings at that point. So every single act, creation, partnership, client goes toward that 5 million valuation. And if it doesn’t, it becomes quite surgical. You just don’t do it. So you’re not wasting productivity.
You’re not wasting time, which is actually the most wealthiest resource out there. The best concept of that and it’s finite so you’re not wasting precious time on things that don’t go towards your exit plan. And then after that, this is the domino effect, you have the hard conversations internally, okay? If you’re talking to your advisory board first, secondary with the other people that you hope would succeed you. If they don’t, you have to look for external buyers. And then with your family, look, I’m planning to sell my company. This could mean some changes. We might not get the same amount of money that we expected. And then also looking for conversations of people that accept some payment or compensation in your family once you get to sell your company. That seems like a whole different episode, Marie. Oh, let’s do it. Amypita. But that’s always an interesting one because it’s like once you sell your company, it’s almost like you won the lottery and everybody comes out of the woodworks, right?
Maureen: Right. Yeah. That whole life cycle of that exit planning is so interesting to me. Yeah. You know, thinking, you know, further down the line in terms of family governance and, you know If it is, it could be your own family, but it could be across generations, it could be multiple families within a family, so it could be cousins, it could be brothers, aunts, uncles, and things like that. It’s more complex.
Sankeetha: Yeah, it’s ironic in the fact that when you have a family business and you think that your children or your relatives will succeed you in the company, but they all choose not to, sometimes it’s ironic that once you sell it to an external third buyer, somehow those children. And relatives come out of the woodwork thinking that they’re going to get part of that payout at the same time.
Maureen: That’s so interesting. I’d love to have that conversation with you. Why don’t we earmark that for later on in the year?
Before we close out, what has surprised you in your career recently?
Sankeetha: So it surprised me how people reinvent themselves. It’s not surprised in a bad way, Maureen. I’m pleasantly gratified when I find this out, where people, after they sell, go and do quite different things, very different things after. It’s almost like this hidden version of themselves that they’ve been slowly hiding or quietly nurturing. Quietly nurturing or slowly hiding either or, but you know many different truths can exist at the same time. And after they sell their company, it’s almost like they’ve given permission for that other side of them to run free and be who they are. And it’s a beautiful thing to see. I’ll be honest, 18 years of doing this, and I still get, again, the word isn’t surprised, pleasantly gratified when that happens. Yeah. So I’m like, oh, this is great. You’re so multidimensional. And that’s the best part because you’re using your time for the parts that would fulfill you.
Maureen: Oh, yeah. So interesting. So, second last question I have is, you and I had lunch down in lower Manhattan the last time I was in town. Can you give us the name of a restaurant that you’ve recently frequented that you really enjoy so that we can get that on our list?
Sankeetha: So we had lunch at the Wall Street or Le Marchand, didn’t we? Yes. Yes, and I really like that. It was lovely. Yes. There’s a new one that’s opened up. I love Tatiana and the Lincoln Center just because the chef has a great fusion of West African as well as Caribbean influences. And he’s got a little bit of Middle Eastern as well too. So Tatiana at Lincoln Center is one that if we can get in, more easy to go.
Maureen: Wonderful. And how can people get in touch with you?
Sankeetha: You can find me on LinkedIn. LinkedIn slash SSelvarajah. You can find me and find my website at ZenseiExits, Z E N S E I E X I T dot com or Sankeetha @ gmail . com I think it’s the best way to contact me.
Maureen: That’s awesome. Sankitha, thank you so much for sharing your time with me today. And I look forward to the next time.
Sankeetha: Absolutely. Thank you so much, Maureen.